Parents Stole Daughter’s Savings to Buy Their Favorite Son a Mercedes
“YOUR BROTHER DESERVES IT MORE!”
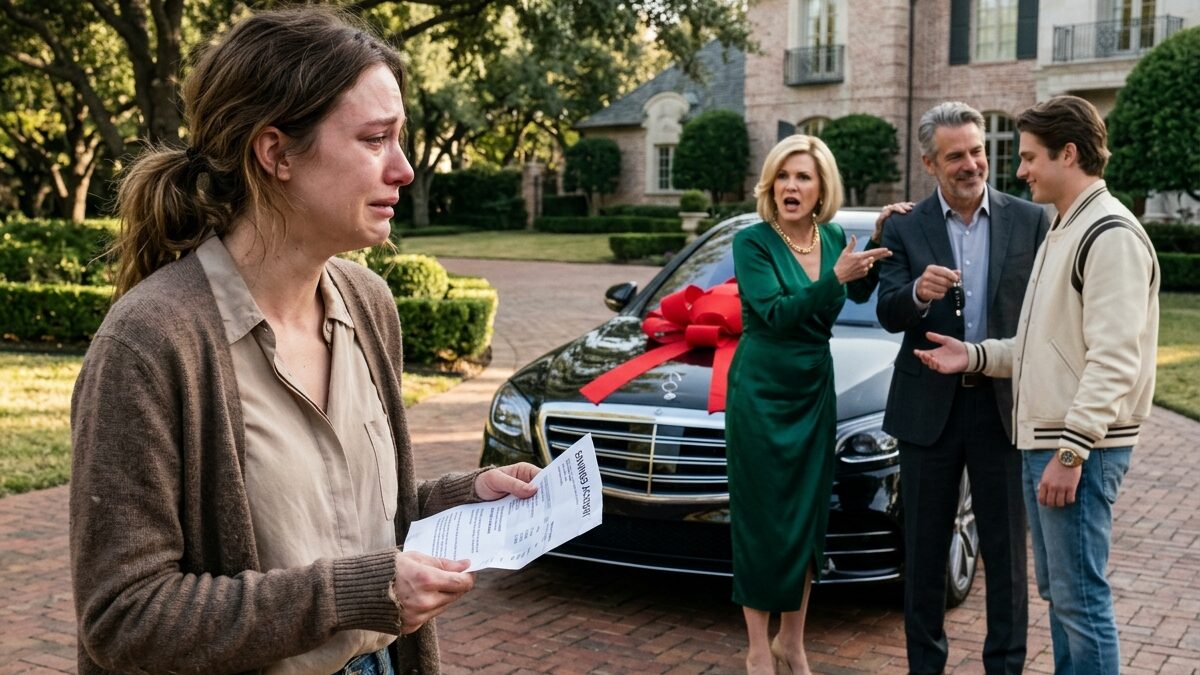
Linda Wilson smiled proudly as her husband handed their son the keys to a brand-new black Mercedes.
An enormous red bow decorated the hood.
Twenty-two-year-old Tyler screamed with excitement.
“Are you serious? This is mine?”
His mother hugged him.
“Of course, sweetheart!”
But standing just a few feet away was their twenty-six-year-old daughter, Emily.
She wore an old brown cardigan and faded jeans.
Her face was pale.
In her trembling hands was a bank statement.
She stared at the luxury car.
Then at her parents.
“THAT WAS MY SAVINGS!”
Linda turned toward her.
“Don’t ruin your brother’s moment.”
Emily shook her head.
“Thirty-eight thousand dollars, Mom!”
Her father, Richard, frowned.
“We’ve already discussed this.”
Emily’s voice broke.
“No! You never discussed it with me!”
Linda grabbed the statement.
“STOP BEING SELFISH!”
Tyler looked between them.
“Wait. What savings?”
Before Emily could answer, a car pulled into the driveway.
Denise Carter, a senior bank representative who had arranged an appointment with Emily nearby, stepped out carrying a transaction report.
She approached Emily and spoke quietly.
“We found the transfer.”
Linda immediately stiffened.
“This is family business.”
Denise looked at the records.
“The money came from Emily’s account.”
Emily turned toward her parents.
“WHO AUTHORIZED IT?”
And the answer would expose years of favoritism—and a financial decision that could permanently change the family.
The Daughter Who Always Had to Sacrifice
Emily Wilson grew up in a comfortable Dallas suburb.
Her parents owned a beautiful house.
Her father worked in commercial real estate, and her mother managed the household.
From the outside, their family seemed fortunate.
But Emily and Tyler were treated very differently.
When Tyler wanted expensive sneakers, Linda bought them.
When Emily needed school supplies, she was told to use the old ones.
When Tyler made the basketball team, the family celebrated at a restaurant.
When Emily received an academic award, her mother said:
“That’s nice. Did you finish your chores?”
Emily learned to avoid complaining.
Her parents called her responsible.
Independent.
Mature.
But those compliments came with an expectation.
She was supposed to need less.
Tyler, meanwhile, was always allowed to need more.
Two Birthdays, Two Different Worlds
On Emily’s eighteenth birthday, her parents gave her a small purse and a greeting card.
“We’re proud of how independent you’ve become,” Richard said.
Emily thanked them.
She didn’t complain.
Four years later, Tyler’s eighteenth birthday looked completely different.
Linda organized a luxury party.
Richard bought him an expensive watch.
They invited dozens of guests.
When Emily quietly asked why the celebrations were so different, Linda replied:
“Your brother has a special future ahead of him.”
Emily stared at her.
“What about my future?”
Linda sighed.
“Don’t start comparing yourself to him.”
That was how every conversation ended.
Tyler deserved the best.
Emily was expected to understand.
The $38,000 Dream
After college, Emily worked as an administrative assistant at a small engineering firm.
She wasn’t earning a fortune.
But she budgeted carefully.
She worked overtime.
Avoided unnecessary purchases.
And rented a modest apartment with a roommate.
Her goal was simple.
She wanted to buy a small home of her own.
Every month, she transferred money into a savings account she’d opened as a teenager.
The account had been established jointly with her father while she was under eighteen.
After becoming an adult, Emily continued using it because she believed her money was safe.
She didn’t realize her father still had broad withdrawal authority as a joint account holder.
Over the years, the balance grew.
Ten thousand dollars.
Twenty thousand.
Thirty thousand.
Then finally, thirty-eight thousand dollars.
Emily cried when she reached that milestone.
She called her mother.
“Mom, I think I can start looking seriously for a home.”
Linda replied:
“That’s nice, honey.”
Then she changed the subject.
“Have you heard Tyler might need another car?”
Emily didn’t think much of the question.
She would soon regret that.
The Favorite Son’s New Mercedes
Tyler had recently complained about his car.
It was only four years old.
But he wanted something more impressive.
His friends drove luxury vehicles, and he felt embarrassed arriving in an ordinary sedan.
One evening, he told his parents:
“I can’t keep driving that thing.”
Richard laughed.
“What’s wrong with it?”
“It’s not the car I want.”
Linda immediately took his side.
“He works hard. He deserves something nice.”
Tyler worked in sales and earned enough to contribute toward a vehicle.
But he didn’t have the money for the Mercedes he wanted.
Richard and Linda agreed to help.
The problem was that they didn’t have enough spare cash available for the planned down payment.
Then Richard remembered the old joint savings account.
He still had access.
He checked the balance.
Thirty-eight thousand dollars.
Money Emily had saved through years of work.
He showed Linda.
She stared at the number.
“That’s a lot sitting in an account.”
Richard hesitated.
“It belongs to Emily.”
Linda waved dismissively.
“She’s not buying a house tomorrow.”
Richard frowned.
“Still—”
“Tyler needs help now.”
That night, they convinced themselves they were simply reallocating family resources.
They planned to tell Emily later.
The Transfer Emily Never Approved
Richard used his legitimate joint-account access to withdraw the savings.
The bank processed the transaction according to the account’s recorded ownership permissions.
The money was transferred toward the dealership payment and associated vehicle expenses.
No one contacted Emily to ask whether she agreed.
Under the account structure, the bank wasn’t necessarily required to obtain her separate permission from the other joint owner.
That legal distinction would later make the situation even more painful.
Emily didn’t know about the transfer until she checked her balance several days later.
The screen showed almost nothing remaining.
She stared at it.
Refreshed the page.
Logged out.
Logged back in.
The money was still gone.
She called the bank immediately.
The representative confirmed a large withdrawal by an authorized account holder.
Emily felt physically sick.
“Who?”
The representative explained that the activity was associated with the other account holder.
Her father.
Emily sat on the floor of her apartment.
For several minutes, she couldn’t move.
“Stop Being Selfish!”
Emily called Richard.
“Dad, did you take money from my savings?”
He sounded uncomfortable.
“We needed to make a family purchase.”
“What purchase?”
A pause.
“Tyler’s car.”
Emily thought she’d misheard.
“Tyler’s what?”
“Your brother needed transportation.”
Emily nearly screamed.
“THIRTY-EIGHT THOUSAND DOLLARS?”
Richard tried to calm her.
“We’ll discuss it this weekend.”
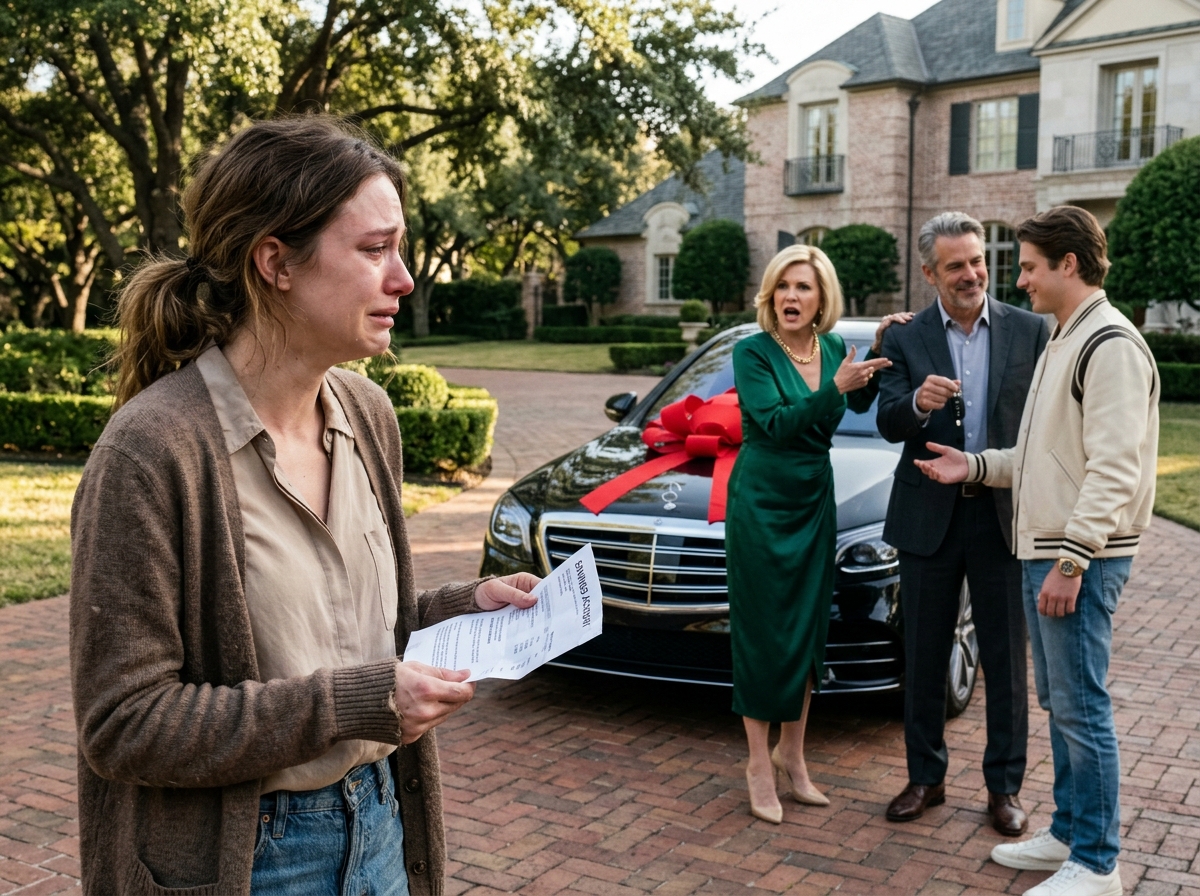
But by the time Emily reached her parents’ house, the Mercedes was already in the driveway.
Tyler stood beside it holding the keys.
Linda was taking photographs.
“Look at our boy!”
Emily stood frozen.
The enormous red bow gleamed in the sunshine.
Linda turned toward her.
“Come take a picture with your brother!”
Emily lifted her bank statement.
“That’s my savings.”
Linda’s smile disappeared.
“Don’t do this now.”
Emily began crying.
“I worked for six years!”
Richard approached.
“We intended to repay you.”
“When?”
He didn’t answer.
Linda stepped forward.
“Your brother deserves this.”
Emily shook her head.
“And I don’t deserve a home?”
Linda frowned.
“Stop being selfish.”
It was the same accusation Emily had heard throughout her childhood.
Whenever Tyler wanted something, Emily was expected to give it up.
But this time, what she’d lost wasn’t a toy or a birthday celebration.
It was six years of savings.
What the Bank Records Revealed
Emily requested a formal review of the transaction.
She contacted the bank’s account services team and asked for copies of the account agreement, ownership records, and withdrawal details.
Denise Carter, a senior representative, helped arrange an appointment to explain what the documents showed.
The transfer was traced to Richard’s authorized access.
Emily was devastated.
She had believed the account was hers alone after reaching adulthood.
But the original joint ownership arrangement had never been changed.
Denise carefully explained the difference between whether a bank was authorized to process a transaction and whether a withdrawal was fair within the family.
The bank’s records did not establish that Emily had agreed to the money being used for Tyler’s car.
Nor did they automatically determine what remedies might exist between the family members.
Emily needed independent legal advice about whether she could recover the money.
But one thing was certain.
Her parents had used her savings without asking.
And they had done it to reward her favored brother.
Tyler Finally Learned the Truth
Until that afternoon, Tyler had believed his parents were financing the car themselves.
When he learned where the money came from, his expression changed.
“You used Emily’s savings?”
Linda sighed.
“She’ll earn more.”
Tyler stared at her.
“Mom, that’s not the point.”
Richard tried to interrupt.
“Tyler, let us handle this.”
But Tyler shook his head.
“No. Emily’s been saving for a home.”
Emily looked at him.
For years, she’d assumed her brother enjoyed the unequal treatment without caring how it affected her.
But now he seemed genuinely shocked.
He placed the car keys on the table.
“I don’t want this if it means stealing her future.”
Linda gasped.
“Tyler!”
He looked directly at his mother.
“You told me this was a gift.”
“It is!”
“Not if you paid for it with Emily’s money.”
For the first time, the favorite son refused to accept the favoritism.
Emily Made a Decision
Emily didn’t immediately forgive anyone.
She consulted a qualified attorney about the account arrangement and the withdrawal.
She also opened a new savings account in her name alone and redirected her paycheck.
Her parents wanted her to treat the situation as a private misunderstanding.
Emily refused.
“This wasn’t a misunderstanding,” she told them.
“You knew what the money was for.”
Richard looked down.
Linda tried to argue.
But Emily continued.
“For years, I’ve been expected to sacrifice so Tyler could have more. I’m not doing it anymore.”
The family eventually agreed to a written repayment plan with legal guidance.
Tyler supported selling the newly purchased car or refinancing the arrangement so the money could be returned.
The actual recovery took time and required cooperation.
But Emily finally had documented commitments rather than vague promises.
She also stopped sharing financial information with her parents.
Her independence was no longer negotiable.
Six Months Later
Six months later, Emily was rebuilding her savings.
The first significant repayment had arrived.
She still couldn’t buy the home she wanted.
But she had a clearer path forward.
Tyler met her for coffee.
He apologized for the ways he’d benefited from their parents’ favoritism.
“I thought they just liked spoiling me,” he admitted.
Emily stared at her cup.
“They did.”
He nodded.
“But I didn’t realize what it was costing you.”
Emily looked up.
“Now you do.”
Their relationship wasn’t magically repaired.
But it was beginning to become more honest.
As for Linda and Richard, Emily kept her distance.
She was willing to discuss repayment and accountability.
She was not willing to return to the old family arrangement.
The Lesson of Parental Favoritism
When parents stole daughter’s savings to buy a luxury car for their favored son, the betrayal went beyond money.
It showed Emily that her parents considered her goals less important than Tyler’s wants.
Parental favoritism can create resentment, financial dependence, and damaged sibling relationships.
It may also teach the overlooked child to accept unfair treatment as the price of belonging.
For general information about joint bank accounts and financial consumer protections, readers can consult the Consumer Financial Protection Bureau.
Joint-account authority and ownership rights vary with account terms and applicable law. A bank processing an authorized withdrawal does not necessarily resolve every dispute between family members.
Emily learned a painful but important lesson.
She couldn’t force her parents to treat their children equally.
But she could protect her own finances and decide which relationships deserved her trust.
Tyler received a Mercedes. Emily paid the price.
Until the truth came out.
Frequently Asked Questions
How much money did Emily lose? Her parents withdrew $38,000 from a savings account she had funded.
Why could Richard access the account? The account was originally opened jointly when Emily was a minor, and Richard remained an authorized joint owner.
Did Tyler know the money came from Emily? No. He believed his parents had paid for the vehicle.
Did Emily recover her savings? The family established a written repayment arrangement, and Emily began receiving repayment, though full recovery took time.
Did Emily forgive her parents? Not immediately. She established financial and emotional boundaries.
What Would You Do?
If your parents used your six years of savings to buy your favorite sibling a luxury car, would you forgive them after they agreed to repay you?
This is a fictional family drama about favoritism, financial betrayal, and boundaries—not financial or legal advice.
Read another family favoritism story: Parents Favor One Daughter—Then Hidden Tuition Payments Expose the Truth